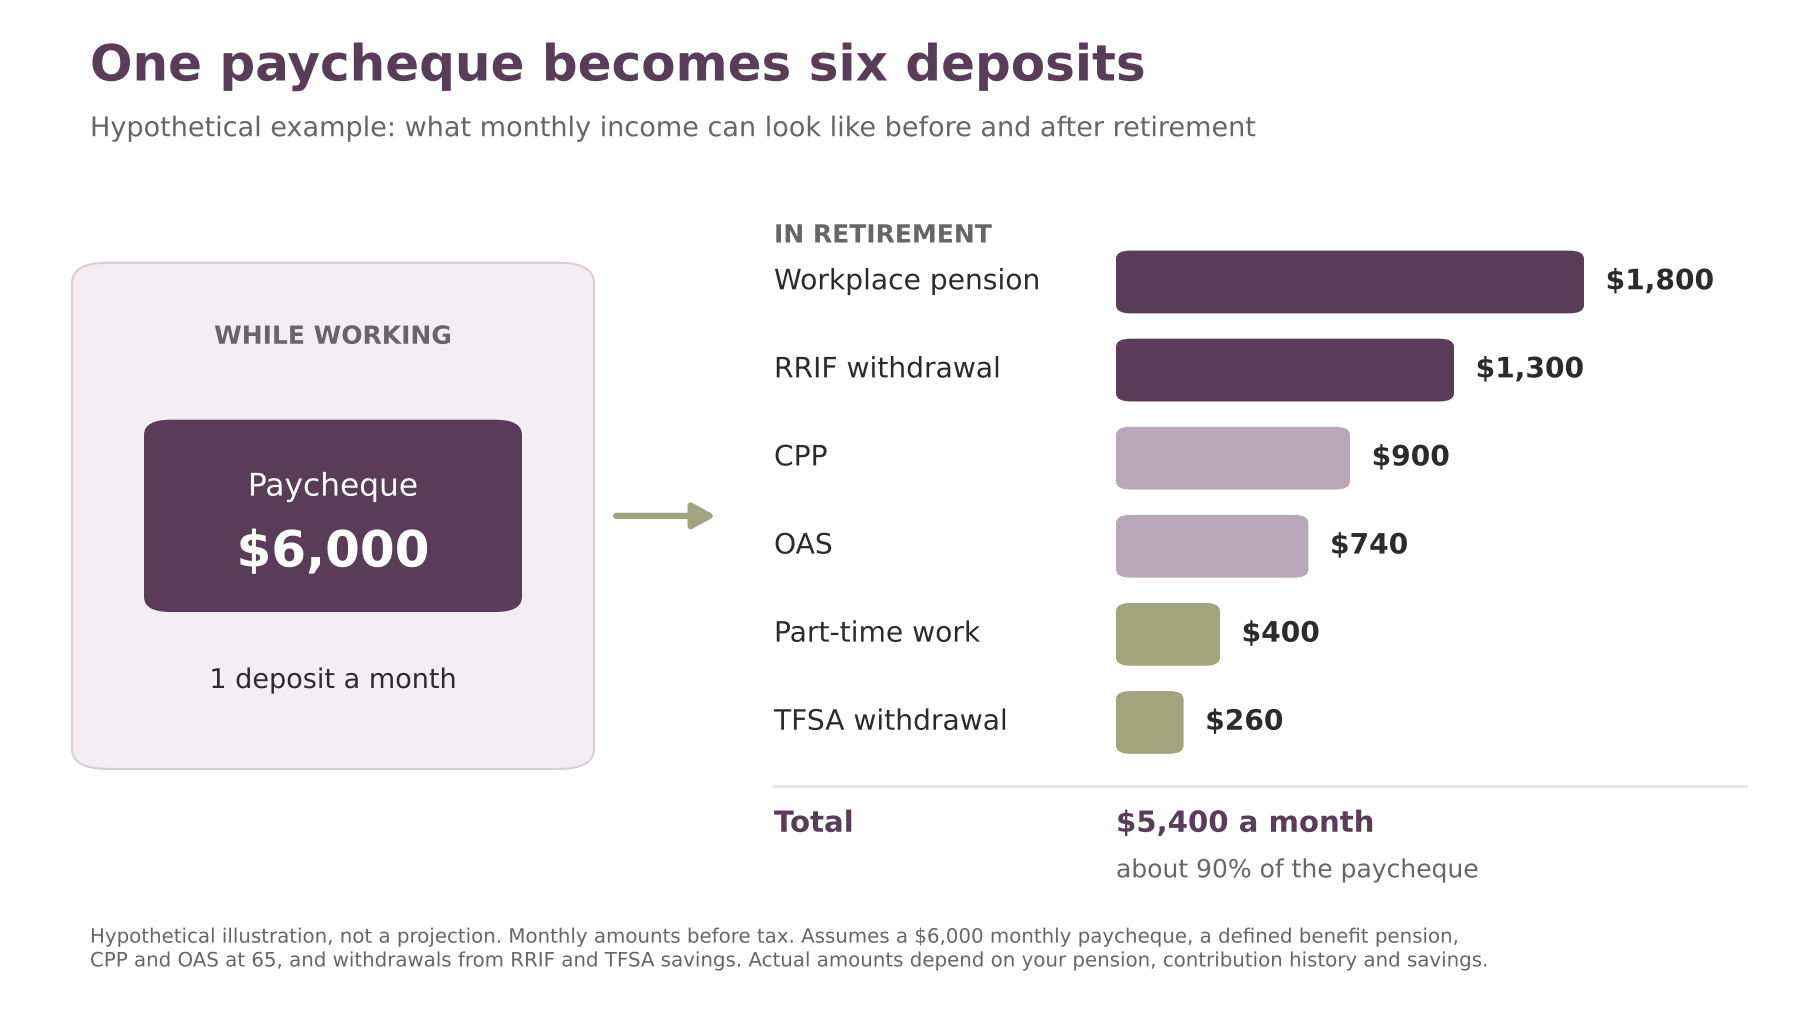
For most of your working life, your income arrives as one paycheque. In retirement, several smaller deposits replace that paycheque, each from a different source. Knowing how those pieces fit together is the difference between retiring with confidence and retiring with a gap.
From one paycheque to several
We see this surprise clients more than almost anything else in retirement planning.
"People are used to one paycheque. The goal when we do the planning is to replace that income with a consistent flow from all of these different sources, so they're still essentially getting a paycheque."
Heidi Blondin, CFP®, EPC
Those sources can include CPP and OAS, a workplace pension, RRIF or LIF withdrawals, a TFSA, non-registered savings and sometimes part-time work. Some people have two; a couple can have a dozen between them.
When the pieces don't add up
This works when the pieces add up. Many people don't know whether theirs do until they sit down with a plan.
"They think, oh, I've got this pension. Well, the pension's not enough to live on. And you add CPP and OAS, and they're like, hmm, that's a little slim."
Heidi Blondin, CFP®, EPC
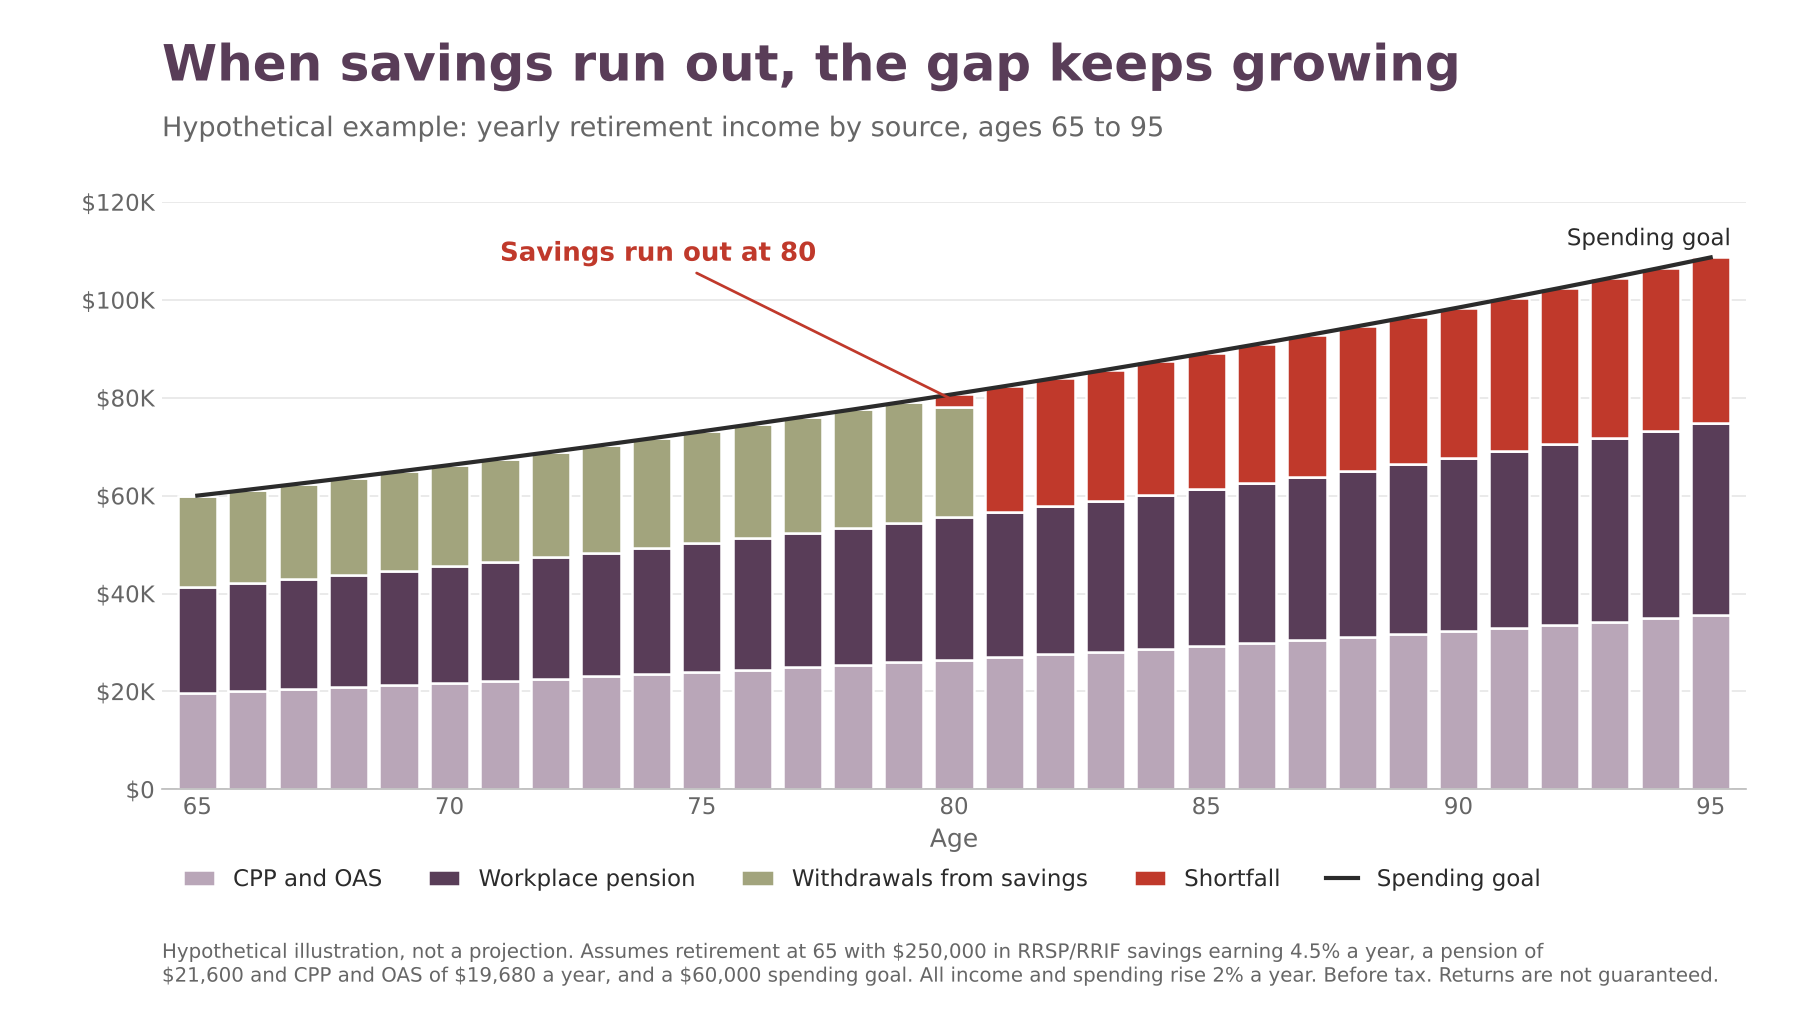
In the example below, savings fill the gap between guaranteed income and spending until age 80. After that, the savings are gone, and the shortfall grows every year because living costs keep rising.
How to close the gap
A shortfall on paper is not a verdict. It is a signal, and the earlier you see it, the more ways there are to fix it:
- Start early. Our rule of thumb is to save 10 to 15% of your before-tax income from the start of your career, including any employer match. If you start later, that number climbs.
- Draw down steadily. In our view, withdrawals of about 4 to 5% a year are generally sustainable for many people, though the right rate depends on your situation.
- Keep some work in the mix. Part-time income in early retirement eases the pressure on your savings.
- Set realistic spending. A plan shows what your sources can support, so you can adjust before you retire rather than after.
Most of all, it helps to know where you stand.
"It's actually less stressful when you know, as opposed to not knowing."
Heidi Blondin, CFP®, EPC
Do your pieces add up?We build retirement income plans that show every source of income you will have and how long it will last.
Mutual funds are offered through Investia Financial Services Inc.
Insurance solutions provided in Ontario and New Brunswick, through Heidi Blondin Financial / Qualified Financial Services.
The comments contained herein are a general discussion of certain issues intended as general information only and should not be relied upon as tax or legal advice. Please obtain independent professional advice, in the context of your particular circumstances. This article was prepared by Heidi Blondin who is a Certified Financial Planner® (CFP) at Heidi Blondin Financial a registered trade name with Investia Financial Services Inc., and does not necessarily reflect the opinion of Investia Financial Services Inc. The information contained in this presentation comes from sources we believe reliable, but we cannot guarantee its accuracy or reliability.