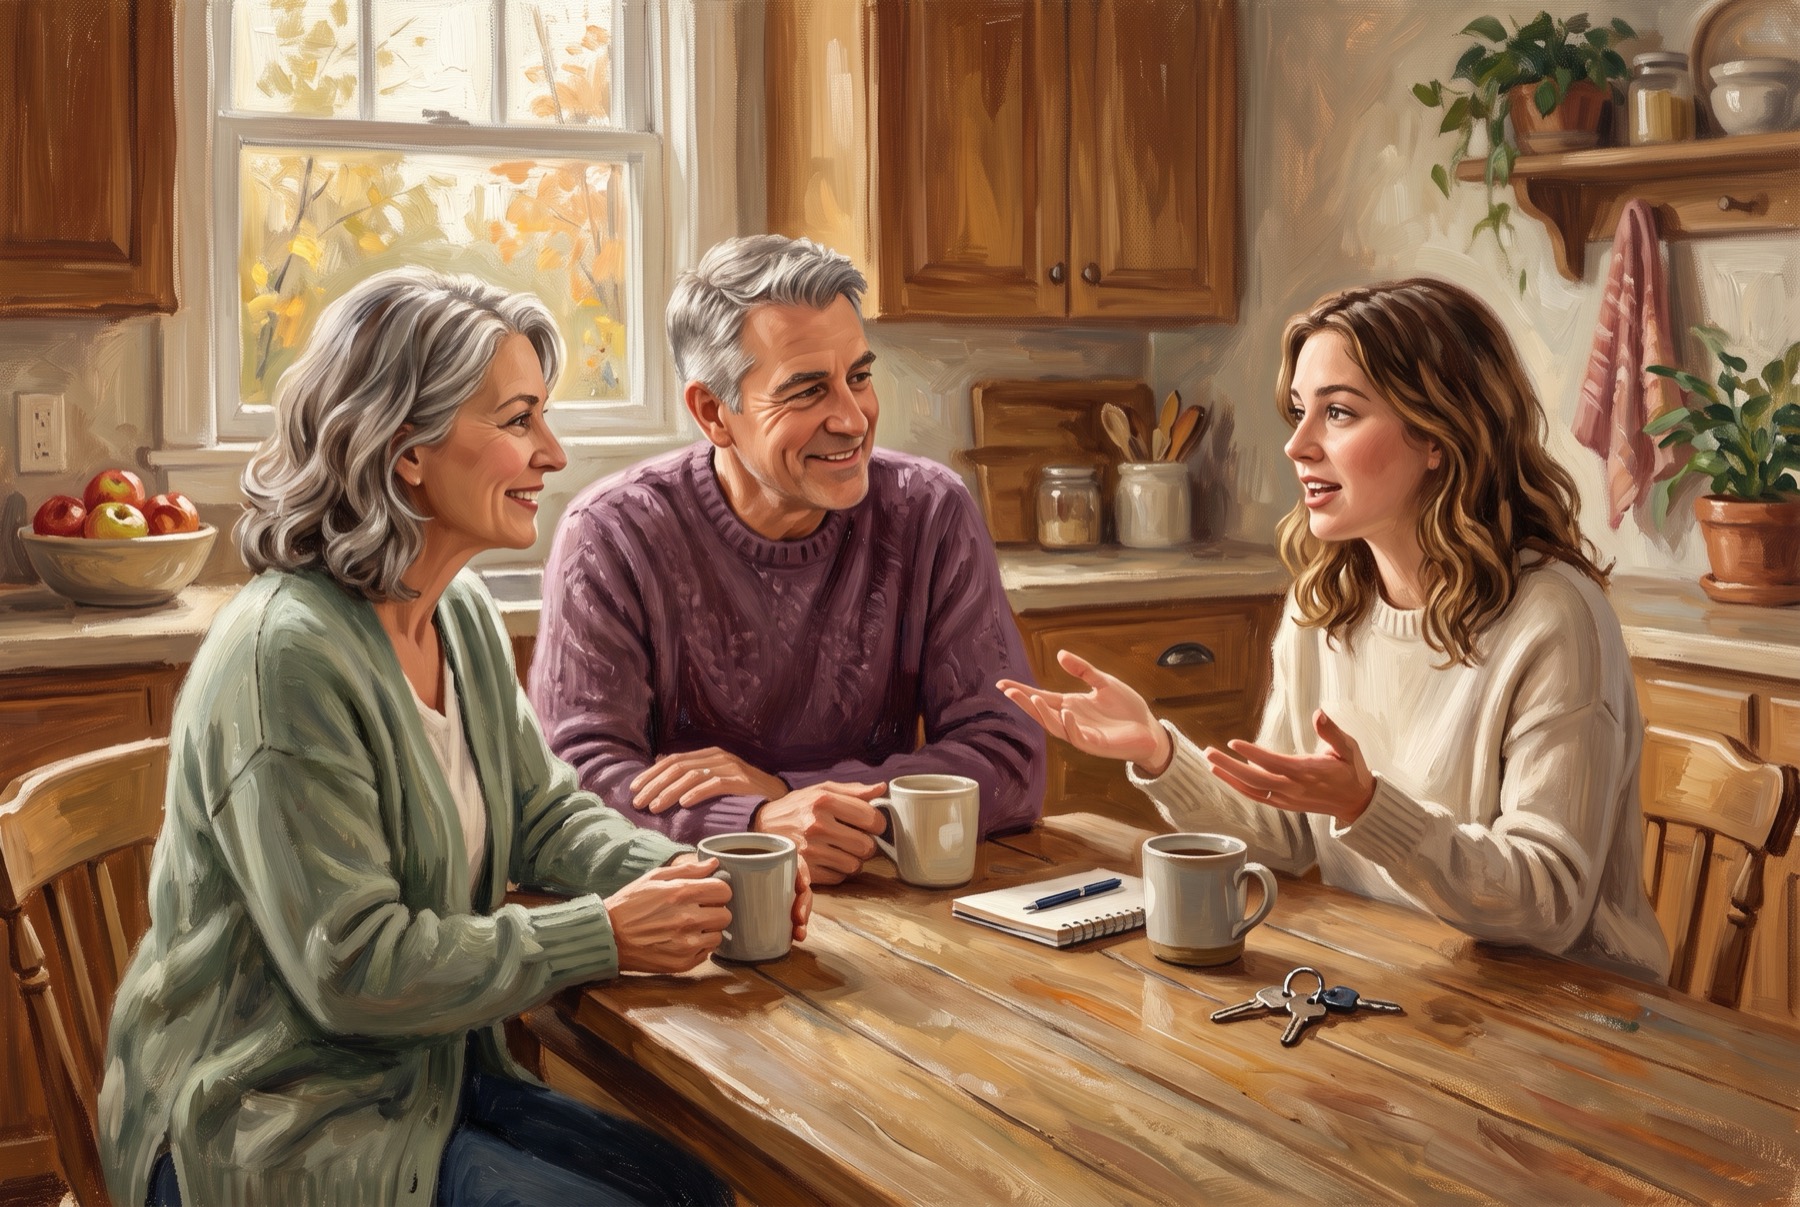
The conversation usually opens the same way. Our kid is twenty-six, still in the basement, and we cannot tell whether helping is helping.
The instinct to step in is a good one. What matters is how, because some kinds of help build something and others just move the same conversation twelve months down the road.
Here are the four routes parents ask about most, from lightest to heaviest.
| The help | What it does | Risk to your plan |
|---|---|---|
| Coach them through it Open an FHSA and a TFSA together, then gift them birthday and holiday money towards those accounts |
Costs nothing but an afternoon. They learn how the accounts work with you beside them, and gift money lands somewhere that compounds instead of somewhere that gets spent. | None |
| Match what they save Dollar for dollar into their TFSA, up to a cap you set |
Rewards the habit instead of replacing it. They still have to do the saving. | Low |
| Cover one specific step First and last month's rent, a move, a certification |
Removes a single barrier with a clear end date. No ongoing obligation. | Low |
| Help with a down payment Sometimes borrowed against your home equity |
Can move them years ahead into the housing market. Also the one that lands on your balance sheet. | Significant |
The home equity conversation
This is the one that comes up most with parents who have paid down a good chunk of their mortgage. The idea is simple enough: borrow against the equity in your home through a line of credit, and use it to help your adult child into the real estate market years earlier than they could manage on their own.
The appeal is that mortgage payments build equity in a property rather than paying rent. Property values can rise and fall, and past performance does not indicate future results.
"This may allow them to enter the housing market earlier than they otherwise could."
It is also the option with the most ways to go wrong, and every one of them is worth naming out loud before anyone signs anything.
- The debt is yours. It is secured against your home, regardless of whose name ends up on the property.
- Line of credit rates move. A payment that fits your budget today may not fit it in three years.
- Borrowing to invest cuts both ways. It magnifies losses exactly the way it magnifies gains, and property values can fall.
- If they cannot carry it, you carry it. Job loss, a breakup, or a rate reset can land the whole thing back on you.
- Put it in writing. Who owns what, who pays what, and what happens if they sell, move, or partner up. Get legal advice on the structure.
Borrowing against home equity involves risks and may not be appropriate for everyone. Families should carefully consider their financial circumstances, debt obligations, cash flow needs and retirement objectives before proceeding.
None of that makes it a bad idea. It makes it a decision that needs numbers rather than enthusiasm, and a plan for what happens if the next few years do not go smoothly.
The line that does not move
Whatever route you pick, it cannot come out of the plan that keeps you independent later.
That is not a reason to sit on your hands. It is the reason to run the numbers on your own retirement first, see what genuine room exists, and then decide how much help is the right amount of help.
Explore how different forms of financial assistance may affect your own long-term financial plan. Heidi and her team can review your situation and discuss strategies that may be appropriate based on your financial goals, retirement objectives and overall circumstances.
Mutual funds are offered through Investia Financial Services Inc.
Insurance solutions provided in Ontario and New Brunswick, through Heidi Blondin Financial / Qualified Financial Services.
The comments contained herein are a general discussion of certain issues intended as general information only and should not be relied upon as tax or legal advice. Please obtain independent professional advice, in the context of your particular circumstances. This article was prepared by Heidi Blondin who is a Certified Financial Planner (CFP) at Heidi Blondin Financial a registered trade name with Investia Financial Services Inc., and does not necessarily reflect the opinion of Investia Financial Services Inc. The information contained in this presentation comes from sources we believe reliable, but we cannot guarantee its accuracy or reliability.